Buying a car with outstanding finance
What happens if you buy a car with finance still owed, how to buy one safely, and what to do if it has already happened.
Updated
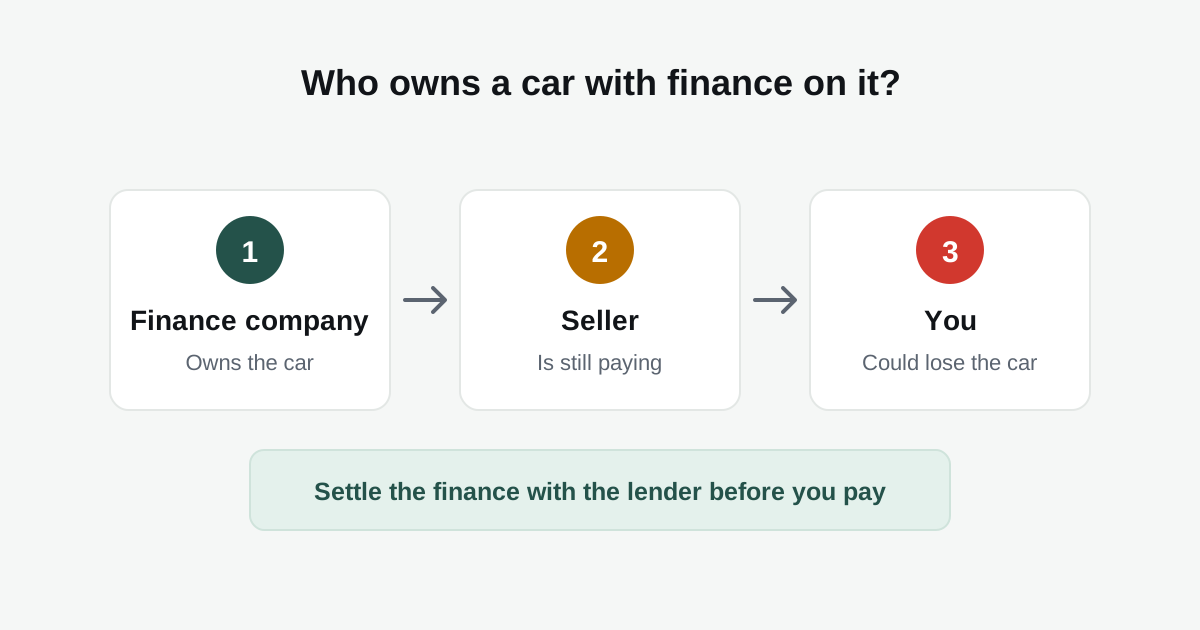
More used cars than you'd think are sold with finance still owing on them. Most of the time the seller simply hasn't thought about it. Sometimes they're hoping you won't check. Either way, if you buy the car and the finance isn't paid off, you could lose the car and the money you paid for it.
Why finance on a car is a problem for you
With hire purchase and PCP, the two most common types of car finance, the finance company owns the car until the last payment is made. The person driving it is just the keeper. So if they sell it before the finance is settled, they're selling something that isn't theirs to sell, and the finance company can try to get the car back from whoever has it.
Logbook loans are similar but work differently: the car is used as security for a loan, and the lender can take it if the loan isn't repaid.
How to find out if there's finance on a car
You can't tell from the car or the V5C logbook. The V5C shows the registered keeper, not the owner. The only reliable way is an outstanding finance check, which searches the records held by finance companies. It's included in our Full check: see what's in each check on our pricing page, or start with a free vehicle check.
Check again just before you pay. Finance can be taken out against a car at any time, so a check from last month isn't enough.
Can you still buy a car with finance on it?
Yes, safely, as long as the finance is paid off as part of the sale. The usual way to do it:
- Ask the seller to get a settlement figure from the finance company. That's the exact amount needed to clear the agreement.
- With the seller's agreement, pay that amount directly to the finance company, not to the seller.
- Get written confirmation from the finance company that the agreement is settled.
- Pay the rest of the price to the seller.
Buying from a dealer? A reputable dealer will settle any finance before selling the car, and should be happy to show you proof. If they won't, buy elsewhere.
What if you've already bought one?
Don't panic, and don't ignore letters from the finance company. Private buyers who bought a car in good faith, without knowing about the finance, may be protected by the Hire Purchase Act 1964 for cars on hire purchase or conditional sale. That can mean the finance company can't take the car from you. But the protection has limits, it doesn't cover everyone or every type of agreement, and proving it can take time.
Get advice early. Citizens Advice is a good free starting point. If you bought from a dealer, you also have rights under the Consumer Rights Act 2015, because they should have sold you a car they had the right to sell.
Red flags
- The seller is reluctant to let you run a history check.
- They want cash, today, and won't wait for you to check anything.
- The address on the V5C isn't where you're viewing the car.
- The price is well below what similar cars are selling for.
Any one of these on its own might have an innocent explanation. Two or more, and it's time to walk away. Our used car checklist covers the other things to check on the day.